Storm Damage Roof Repair in Audubon, New Orleans
Grand early-1900s houses facing the park and the university campuses, on some of the largest residential roofs in the city. Slate, tile and long shingle runs, all under mature live oak.
- Audubon Park and campus corridor
- Large roof areas, long runs
- Slate, tile and heavy shingle
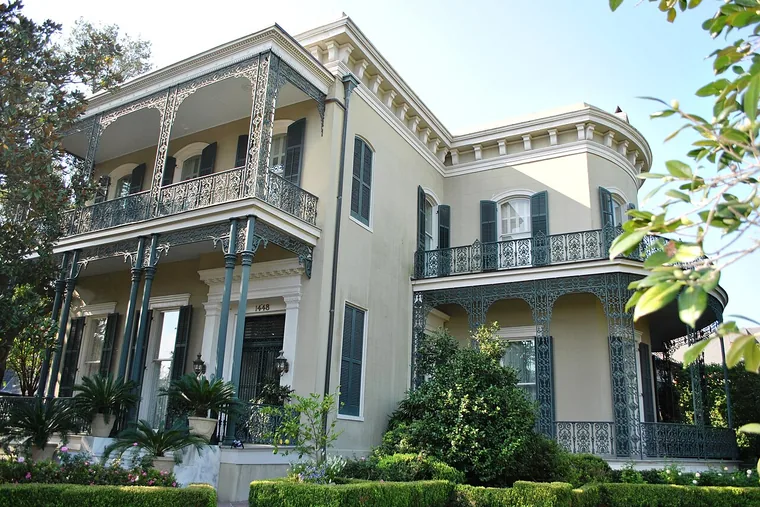
Audubon building stock, and what it means for a roof
Audubon sits between the park and the river, wrapped around the Tulane and Loyola campuses. The housing is early-twentieth-century and built to a scale that matches the setting — wide detached houses with deep porches, substantial roofs, and in many cases slate or clay tile chosen when those materials were the default for a house of that standing.
The practical consequence is roof area. These are among the largest residential roofs in New Orleans, with long uninterrupted runs that need proper staging rather than ladder access, and enough surface that a small percentage failure is still a significant repair. The live oak canopy around the park adds the same debris load the rest of Uptown deals with.
Why Audubon roofs fail the way they do
Three things we see repeatedly on this stock — not a generic list, and not the same three as the next neighborhood over.
Long-run fixings
Extended slopes expose fixings to more thermal movement. Nail pops and lifted courses show up mid-run, not at the edges.
Tile slippage
Clay tile on a large roof shifts over decades. A handful of displaced tiles opens the underlayment to driven rain.
Gutter capacity
A big roof in a 63-inch-a-year rainfall city overwhelms undersized guttering, and the overflow lands at the foundation.
What hurricane damage actually looks like
Gulf Coast storm damage is a wind-uplift story. Most of it is invisible from the street, which is exactly why claims get underpaid.
Lifted but not missing
Wind breaks the seal strip and lifts a shingle without taking it away. It lies back down looking normal and lets water under from then on.
Ridge and rake loss
Uplift starts at the edges. Ridge caps and rake courses go first, and they are the hardest lines to see from ground level.
Displaced slate and tile
On historic roofs wind slips units rather than removing them. A handful of moved slates opens the underlayment to driven rain.
Flashing pulled open
Chimney, wall and valley flashing works loose under sustained wind load and stays open afterwards.
Debris strike
Live oak limbs are the usual culprit here. A strike can fracture decking without leaving an obvious hole in the covering.
Wind-driven rain intrusion
Water forced horizontally under courses and into vents, with no covering damage visible at all afterwards.
How the claim runs
- Inspect and document. Photographs of every damaged element, dated, with the damage mechanism described in writing.
- You file. The claim is yours to file — we give you the documentation to file it with.
- Adjuster meeting. We meet your adjuster on the roof and walk them through what we found, so the scope is agreed on the roof rather than argued afterwards.
- Repair and close out. The approved scope is carried out and documented for the file.
What we cannot do for you
We are not your insurer and we are not public adjusters. We cannot promise a claim outcome, tell you your policy covers something, or negotiate on your behalf. What we can do is document what the storm did, accurately and thoroughly, so the decision is made on evidence. Anyone promising you a guaranteed approval before they have been on the roof is telling you what you want to hear.
The season, and what it asks of a roof
Gulf Coast roof failure is a wind story, not a hail story. The damage that matters is uplift — seals broken, edges lifted, water driven under what is left.
The window for finding lifted edges, tired flashing and loose ridge caps while there is still time to fix them calmly and at a normal price.
Peak season. Demand spikes, good crews book out, and the roofs that get attention first are the ones already on somebody’s list.
Nobody credible puts a crew on a roof while it is still blowing. We take the call, log the address, and move the moment conditions allow.
Make safe, dry in, document for the claim, then diagnose properly in daylight. In that order, and not all in one visit.
Four stages, no surprises
Inspection
Someone goes onto the roof. Not a drive-by, not a satellite image — the covering, the flashing, the valleys and the deck condition, looked at directly.
Diagnosis
What has failed and why, traced to the actual entry point rather than the spot where water shows up inside.
Written scope
What we found, what we propose, and what it costs, in writing with photographs. No number quoted cold over the phone.
The work
Carried out to the agreed scope, dried in each day, site cleared, and documented for your records and your insurer.
Working around Audubon Park, Audubon Zoo, Tulane University and the surrounding streets. If your address is in Audubon, it is in the service area — there is no travel surcharge anywhere inside Orleans Parish.
Storm Damage Roof Repair near Audubon
Everything else we do in Audubon
Storm Damage Roof Repair in Audubon — straight answers
Can you guarantee my insurance claim gets approved?
No, and anyone who does is telling you what you want to hear. We are not your insurer and we are not public adjusters. What we do is document what the storm actually did, thoroughly and with dated photographs, so the decision gets made on evidence rather than on a guess.
My roof looks fine from the street — can there still be storm damage?
Frequently, yes. Gulf Coast wind damage is mostly uplift: seals broken and shingles lifted then laid back down, ridge and rake courses started, flashing pulled open. Almost none of that is visible from ground level, which is exactly why this damage gets missed and claims get underpaid.
How soon after a storm should I have it looked at?
As soon as it is safe. Documentation is strongest close to the event, and an opening that is left through the next rain turns a roof claim into a roof-and-interior claim.
My roof is large — will you quote per square or for the whole job?
For the whole job, in writing, after someone has been on the roof. Per-square pricing quoted over the phone is where large-roof jobs go wrong, because it assumes the decking, the flashing and the valley metal are all in the condition the caller thinks they are. On a roof this size that assumption is expensive when it turns out to be wrong.
Storm Damage Roof Repair in Audubon?
Call and we will get someone on the roof, then put what we find in writing.